


Just 48 hours ahead of the US jobs report, a private payrolls reading showed hiring at companies grew at the slowest pace since the start of the year. Meantime, the services sector expanded by the most in nine months, powered by the largest monthly gain in a measure of business activity since 2021.
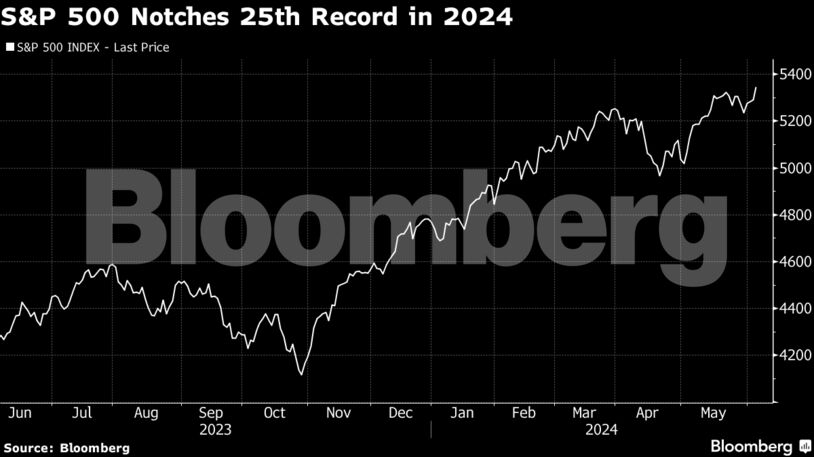
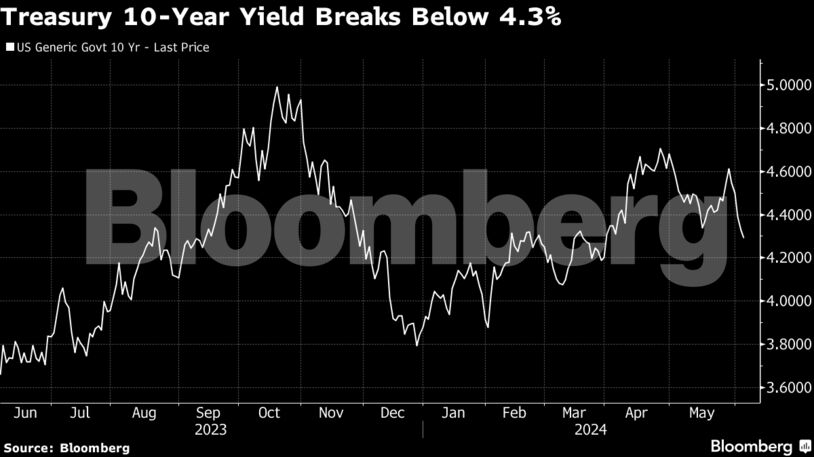
The S&P 500 rose 1.2% to close above 5,350. Treasury 10-year yields dropped four basis points to 4.28%. Swap contracts continued to show bets on a first Fed cut in November, and possibly another in December.
The loonie fell after the Bank of Canada became the first Group of Seven central bank to kick off an easing cycle. The euro edged lower, with the European Central Bank expected on Thursday to start a rate cutting cycle before the Fed for the first time ever. The Japanese yen dropped almost 1%. Bitcoin topped $71,000.
Investors are refocusing on megacaps, and for good reason, according to Ed Clissold at Ned Davis Research.
“US megacaps have become investor favorites due to their ability to generate enough cash flow to both reinvest it into their businesses, with AI being the recent favorite, and return it to shareholders via dividends and buybacks,” Clissold said.
A “wall of money” from passive equity allocations will pour into the stock market in early July, setting up a continuing rally through the early summer, according to Goldman Sachs Group Inc.’s Scott Rubner.
Since 1928, the first 15 days of July have been the best two-week trading period of the year for equities, and they tend to fade after July 17, according to Rubner. The S&P 500 has been positive for nine straight Julys, posting an average return of 3.7%. The Nasdaq 100 has an even better record, posting gains in 16 straight Julys, with an average return of 4.6%, he noted.
“The slow and steady march higher for equity markets continues to confound the bears,” said Mark Hackett at Nationwide. “The latest stretch is being attributed to shifting views of Fed policy, though the more accurate reason is that buying pressure from retail and institutional investors, share buybacks, and growing M&A activity provides a healthy backdrop.”
With earnings season basically over, the focus now turns back to the macro data — and that may impact stocks near-term, according to Gillian Wolff at Bloomberg Intelligence.
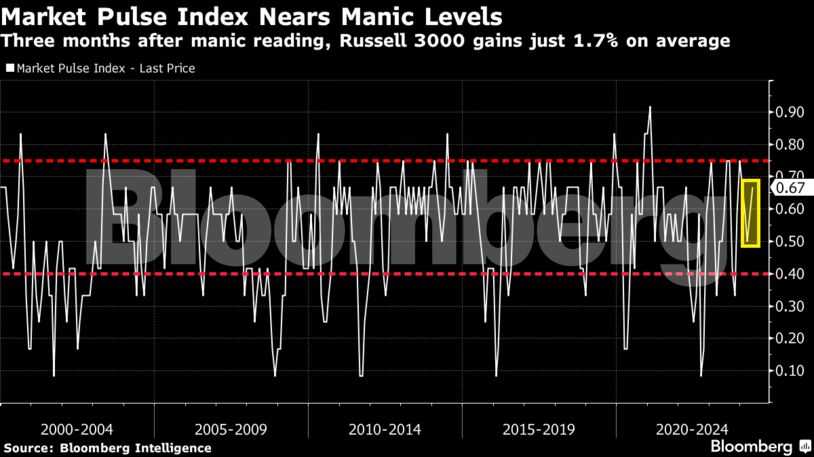
The Bloomberg Intelligence Market Pulse Index, a sentiment gauge that acts as a contrarian signal, advanced within striking distance of “manic” territory last month. It’s a rare sign that has typically tempered US stock returns in the short-run. In the three months following a manic reading, the Russell 3000 Index has gained an average 1.7%, compared with 9.1% after panic.
With the Fed widely expected to stay on hold next week, the focus of the meeting will be the new Summary of Economic Projections. Back in March, Fed officials maintained their outlook for three rate cuts in 2024.
“The ‘dots’ are likely to cluster around one or two interest rate cuts this year,” said Stephen Brown at Capital Economics. “Nevertheless, as inflation falls a bit faster than officials expect and GDP growth disappoints, our base case remains that the Fed will cut in September.”
Corporate Highlights:
Take the MLIV Pulse survey
Will the election help UK markets shed the Brexit premium? Share your views.
Key events this week:
Some of the main moves in markets:
Stocks
The S&P 500 Index surged 1.2% to 5,354.03 as of 4:20 p.m. New York time.
The Dow Jones Industrial Average gained 0.2% to 38,807.33.
The Nasdaq Composite Index surged 2% to 17,187.91.
The MSCI All-Country World Index jumped 0.9% to 794.73.
Currencies
The Bloomberg Dollar Spot Index was little changed at 1,251.86.
The euro fell 0.1% to $1.0871.
The British pound climbed 0.2% to $1.279.
The Japanese yen weakened 0.8% to 156.13 per dollar.
Bitcoin jumped 1.3% to $71,318.
Bonds
The yield on 10-year Treasuries decreased four basis points to 4.28%.
Germany’s 10-year yield fell two basis points to 2.51%.
Britain’s 10-year yield gained one basis point to 4.184%.
Commodities
The Bloomberg Commodity Index advanced 0.6% to 101.87.
West Texas Intermediate crude climbed 1.2% to $74.16 a barrel.
Gold strengthened 1.1% to $2,353.48 an ounce.
This article is more than a year old
Newsdeck
S&P 500 Hits 25th Record This Year as Tech Soars: Markets Wrap
The world’s largest technology companies drove stocks to all-time highs, while bond yields fell with traders almost fully pricing in two Federal Reserve rate cuts in 2024.
Comments
Scroll down to load comments...