


This is a modal window.
That said, Friday brought another set of mixed readings on the economy. US consumer sentiment rose in early August for the first time in five months on more optimistic expectations about their finances as inflation steadied. The caveat is: the rise in sentiment was partially driven by political reasons after President Joe Biden’s decision not to seek re-election. New-home construction sank to the lowest since the aftermath of the pandemic.
“Investors should expect more volatility in the near term as the economic data likely give conflicting signals,” said Jeff Roach at LPL Financial.
The S&P 500 hovered near 5,550. Most megacaps gained, with Alphabet Inc. leading the charge. Applied Materials Inc. sank after a sales forecast that disappointed investors looking for a bigger payoff from artificial-intelligence spending. Wall Street’s “fear gauge” - the VIX - dropped below 15.
Treasury 10-year yields fell one basis ppoint to 3.9%. The dollar dropped. Gold briefly topped $2,500, bolstered by hopes that the Fed is edging closer to cutting rates. Oil sank, with traders weighing the impact of a slowdown in China against a possible attack by Iran or proxies on Israel.
Fed Chair Powell will speak next Friday at the Kansas City Fed’s Jackson Hole Economic Policy Symposium.
With the central bank on the cusp of lowering interest rates from a more than two-decade high, Powell’s comments will be closely parsed for any hints on how the Fed chief is viewing the economy in the wake of a weaker-than-expected jobs report and further easing in inflation.
“The main message in Powell’s speech will likely be that monetary policy overall has worked as intended, and the current level of rates is restrictive,” said Anna Wong at Bloomberg Economics. “He may say the balance of risk between the Fed’s mandates - employment and inflation - is about even. We expect him to signal a rate cut is coming, but not to indicate whether it will be 25 basis points or 50 bps. That will depend on the August jobs report.”
Five Big Questions for the Fed at Jackson Hole: Bill Dudley
Next week’s Jackson Hole symposium will be the “perfect platform” for the Fed to set policy expectations for September, according to TD Securities’ strategists.
“We look for Powell to signal that given recent progress, the Fed is likely to ease policy next month, without fully committing to the size of the rate cut,” they noted. “We expect a 25 basis-point reduction. The July FOMC minutes will offer a preview around easing discussions on Wednesday.”
While recent data have indicated that a 25-basis point cut in September seems more probable than a bigger reduction, given the Fed’s increasing emphasis on the labor market, the next jobs report will be crucial in determining the final decision, according to Fawad Razaqzada at City Index and Forex.com
“Still any strong hints of a cut in September at the Jackson Hole symposium could send the dollar lower and underpin the gold forecast,” he said.
At Bank of America Corp., Ralf Preusser says the next few weeks will likely determine whether the Fed ends up cutting by 50-75 basis points this year or more aggressively.
“We maintain a bullish bias in US rates, and would see a Jackson Hole-induced selloff as an opportunity to buy,” he noted.
Corporate Highlights:
Some of the main moves in markets:
Stocks
Currencies
Cryptocurrencies
Bonds
Commodities
This story was produced with the assistance of Bloomberg Automation.
This article is more than a year old
Newsdeck
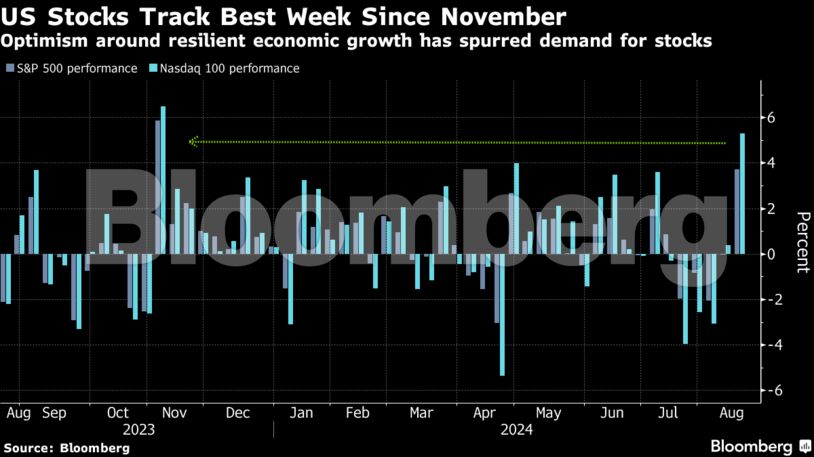
Stocks Poised to Close Out Their Best Week of 2024: Markets Wrap
The stock market is on track for its best week in 2024 as traders assessed the latest economic data for clues on the outlook for Federal Reserve policy.
The media could not be loaded, either because the server or network failed or because the format is not supported.
Comments
Scroll down to load comments...